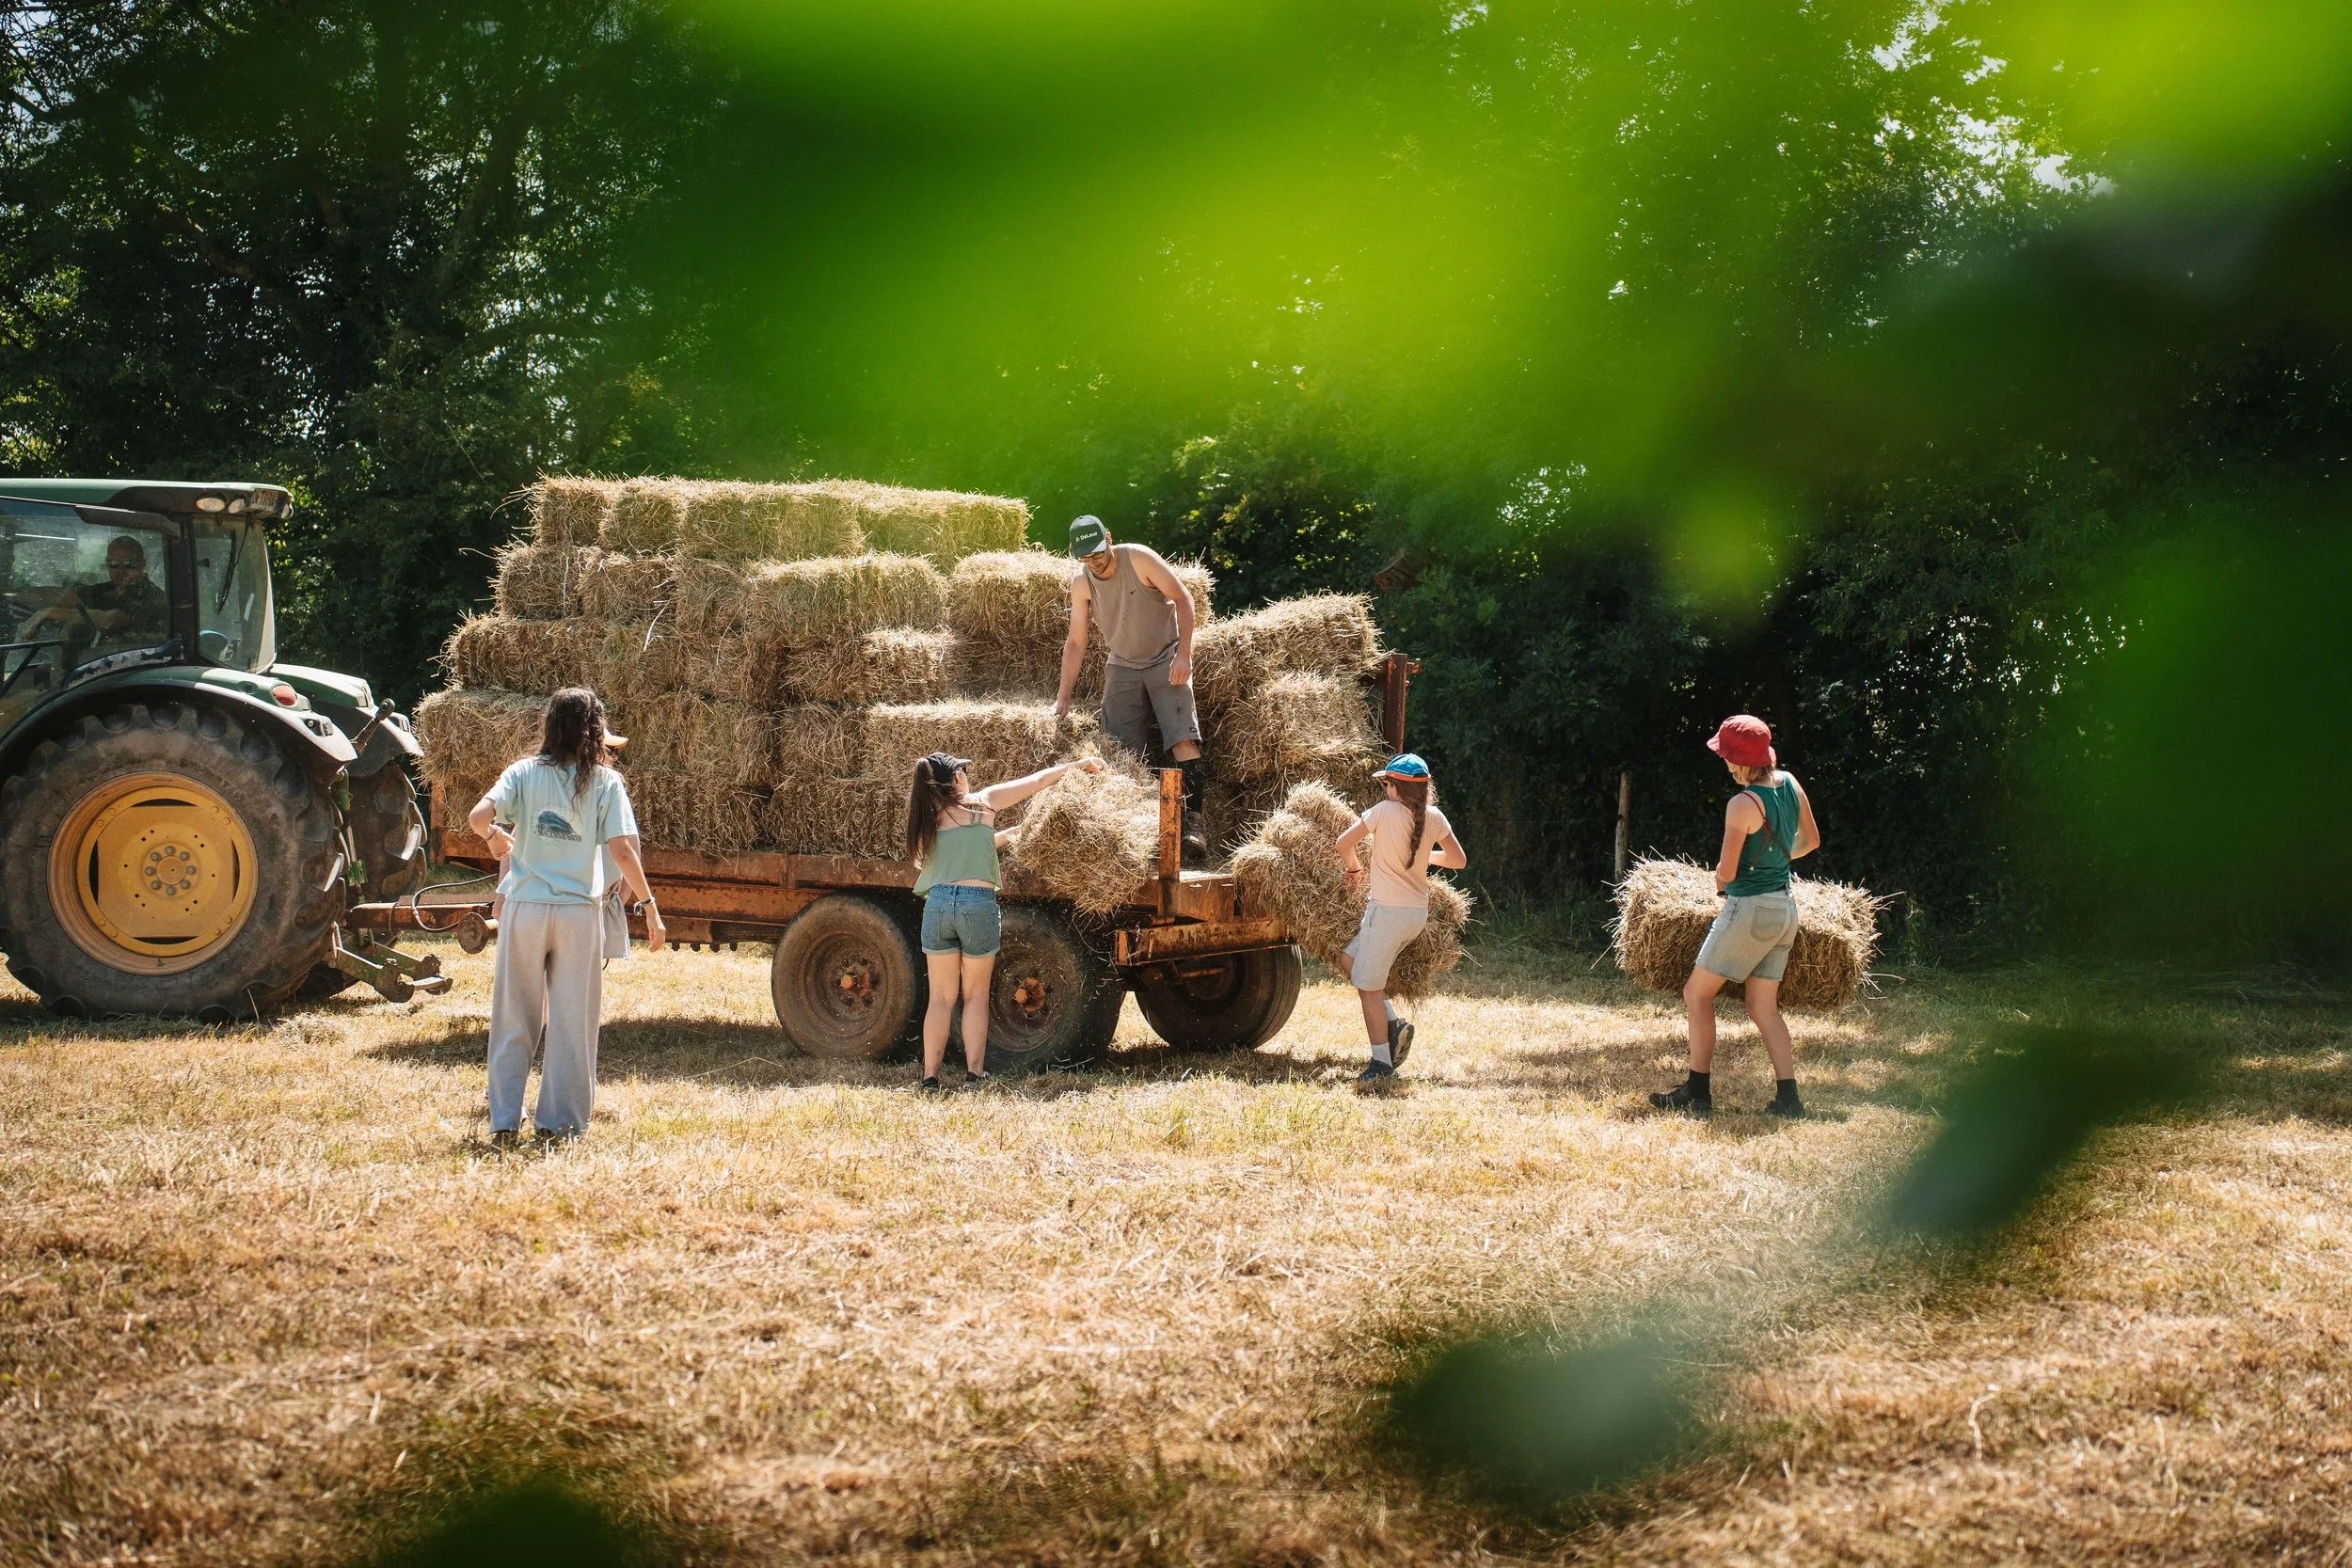
Aristotle is reported to have said that the worst form of inequality is to try to make unequal things equal. Few areas of planning prove the point like passing on a family farm or ranch.
In almost every farm and ranch family we work with, one or more children want to carry on the operation, and others have built lives elsewhere. Deciding how to treat the children who don't farm is usually the hardest part of the plan. It is also where well-meaning parents most often make choices that put the operation, or the family, at risk.
We think of farm and ranch succession planning as a process of decision making with three objectives:
Protect the ongoing viability of the agricultural operation;
Provide for an orderly transition of the operation to new ownership; and
Preserve family harmony.
The Basic Problem: Two Kinds of Owners with Opposite Goals
The child who farms wants secure control of the land, equipment, and water rights the operation depends on. They want profits reinvested so the operation can grow, and they want to reap the benefits of the growth their own work produces.
The children who don't farm usually want something different. Some feel a sentimental tie to the land, but most would rather have their share in a form they can use. As owners, they tend to want cash distributions, not reinvestment.
Put both groups into equal co-ownership of the farm and those goals collide. Every decision about buying equipment, renting ground, or holding back cash for a bad year can become a family argument. Trying to make things equal by giving every child a piece of the operation is one of the most common ways a farm transition fails.
Fair Almost Never Means Equal
Most parents want to treat their children fairly, and many assume that means leaving each child assets of equal value. With a family farm or ranch, an equal split is rarely fair to anyone and will often jeopardize everything.
A dollar of farmland is not a dollar of cash. A child who inherits $1,000,000 in cash can invest it and draw income with no further work. A child who inherits $1,000,000 in farmland must keep working it and may never net anything close to the income from the land the other child is able to generate from the cash.
Equal ignores sweat equity. The child who came home to farm has often spent years accepting lower wages, giving up other opportunities, and building the value of the operation. An equal split hands much of that value to siblings who didn't help create it. Consider the example of Robert. His parents asked him to come home and eventually take over the farm, at a salary of $52,000 a year. His three siblings have no interest in farming. Because the parents want to treat their children equally, they pay Robert $250 a week and pay each sibling $250 a week too. Nobody would call that fair while the parents are alive. It isn't any fairer after they die.
The better aim is an equitable plan, not an equal one.
Questions to Answer Before You Plan
Before choosing any tool, we ask parents to work through these questions:
Is your first goal to keep the operation in the family, or to treat every child equally? It is hard to fully achieve both.
Has the child who farms helped grow the value of the operation? If so, is it fair to pass that added value to the children who didn't take part?
What will each asset actually be worth to the child who receives it, in usable income and flexibility?
Can the operation's cash flow support buying out the other children, and on what timeline?
What will keep your children on speaking terms after you're gone?
Tools for an Equitable Plan
A farm's cash flow is rarely large enough to fund a fully proportional inheritance for every child. That doesn't mean the children who don't farm must be left out. It means the plan has to be built deliberately, usually with several of these tools working together.
Use assets outside the operation. Investments, retirement accounts, a home, or land the operation doesn't need can go to the children who don't farm. Remember that a smaller cash inheritance may still produce more income than the farming child will ever draw from the operation.
Sell the operation to the farming child at a set price. A purchase agreement, often paid in installments, lets the farming child buy out the parents or siblings on terms the operation can support. Setting the price and terms in advance avoids an argument over value later.
Fund the difference with life insurance. A life insurance policy on the parents can provide the non-farming children's inheritance in cash, so the operation itself stays intact. If the farming child is buying the operation, paying premiums may take less cash than making note payments.
Setting up Life Insurance in a Farm Transition Plan
In a farm transition, life insurance can provide an inheritance for children who don't farm, fund a buyout of siblings, cover long-term care costs for the parents, or provide cash to pay estate taxes. It is a tool. Nothing more or less. As with any tool, the questions are whether there is a real need, what the alternatives are, and what the most economical way to meet the need is.
If insurance is part of the plan, these are the decisions that matter:
Permanent or term. Term costs less, but it may lapse before it is needed. For an inheritance or buyout, a permanent policy is usually the safer choice. Remember, permanent problems require permanent solutions.
One life or second-to-die. A policy on one parent gives the surviving spouse cash. A second-to-die policy pays when both parents have died, which is often when the farm passes, and it can cost less and be easier to qualify for.
How premiums are paid over time. Premiums can become hard to afford as parents age. We often recommend structuring the policy to be paid up over a set number of years, so it pays for itself after that.
Who pays. It is natural to assume the parents should pay, but often the farming child should. That child benefits most when the proceeds fund a sibling buyout or protect the operation from long-term care costs.
Start early. Age and health drive the cost and availability of coverage, so look into it sooner rather than later.
Equitable, not Equal
There is rarely a simple answer to how a farm or ranch should pass to the next generation. Moving from "equal" to "equitable" opens options that an equal split closes off. The best plans usually combine several tools: a fair price for the farming child, a real inheritance for the others, and an agreement everyone understands before it is needed.
If you are beginning to think about your own transition, we would be glad to help you and your family work through these decisions. Contact us to schedule a consultation.
This post is for informational purposes only and not for the purpose of providing legal advice. You should contact an attorney to obtain advice with respect to any particular issue or problem. Nothing herein creates an attorney-client relationship between Hallock & Hallock and the reader.